

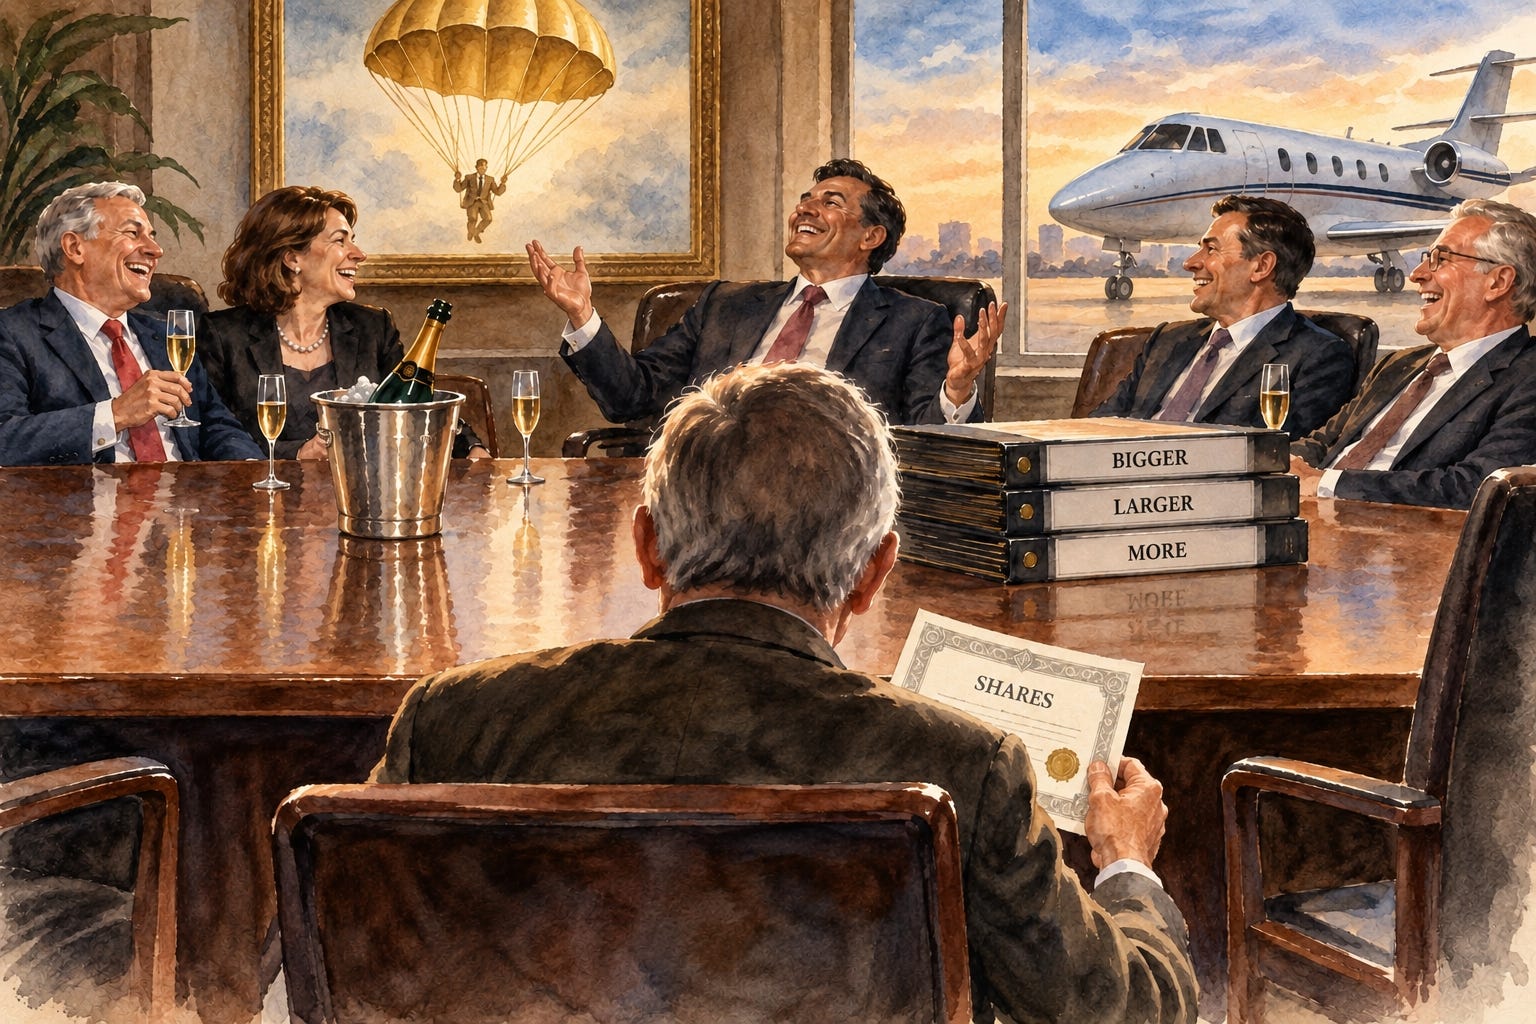
A board of directors has a fiduciary responsibility to act in the interests of the company and its shareholders. In practice, plenty of company managements and boards treat that duty the way a teenager treats a curfew: acknowledged and ignored.
Start with what management and directors actually owe owners. First and foremost, they should be working to make morally and honestly obtained profit.
Management works hard, often for years. They have to fight for funding, fight the regulators, fight their own compliance staff, fight for every little bit of progress. Finally, if they are good and lucky, the business becomes profitable, and even starts generating positive cash flow. Their job now becomes deciding what to do with the cash a profitable business throws off. Whether to reinvest it at high returns, pay it out as dividends, buy back stock below intrinsic value, retire debt, or pursue an acquisition the purpose of which is to make more profit.
Or, given that they have struggled so hard, should they keep that profit and cash flow under their own control? Because they fought for capital for so long, and now they don’t have to. Or because they think they know what to do with the profit better than their investors know what to do with it. This is where things start going south.
Consider a mid-cap company. The CEO wants a bigger company, in part because a bigger company means a bigger salary and a resumé that appeals to search firms specializing in filling board positions. So he buys a competitor at a premium, funds it with debt or dilutive stock, calls it strategic, and adds an achievement to his resumé. The stock does nothing for a decade. But he gets a new jet allowance and a golden parachute sized to reward the empire-building that wrecked the balance sheet while providing insurance against accountability.
Peter Lynch called this diworsification.
The malincentives run deeper than one bad acquisition. Compensation committees are often composed of directors who are management in other companies. Directors sit on one another’s boards and vote on one another’s executive pay packages. They may tie executive bonuses to revenue growth, headcount, or total assets under management rather than return on invested capital or free cash flow per share. Grow an empire, and the bonus grows with it, whether or not a single shareholder ever receives a dollar back. But close a division that doesn’t earn its cost of capital, and the same executive takes a pay cut for doing the right thing.
Nobody in that boardroom or management is stupid. The incentives are just pointed at the wrong target. People respond to incentives.
In a small new company, the motivations are often different. The CEO is likely a founder, and passionately driven to accomplish his goal, which may involve bringing his invention to production, successfully identifying a new resource on land he gambled on, or introducing a product to the masses.
An essential component of success in a new venture is the willingness of the founder to push aside the many naysayers who advise against doing anything so insane as starting this business. He proceeds despite them all, and succeeds as a result of that conviction. But that required characteristic of success—ignoring all those naysayers—is exactly the same personality characteristic that leads to humiliating failure and bankruptcy.
Profit is not his priority. Return to shareholders is not his priority. Success—as the founder defines it—is his priority. This is one of many reasons why founders are not always the optimal people to lead a small company.
Be careful when other people are making decisions with your money. They won’t care as much as you do. The person who behaves as a true fiduciary is the rare exception.
What can help?
Aligning the incentives of management with the investment returns to the owners is essential.
Most directors and C-level managers should own shares purchased with their own cash, in an amount that is a meaningful portion of their own net worth. Cash compensation in part can be replaced (not supplemented, but replaced) with stock grants, not as a method of getting more compensation, but to align incentives. A board should be well populated with investors most interested in ROI.
Management compensation should be tied to return on invested capital, not revenue, and preferably not for accomplishing intermediate goals. And not for how well they advance diversity and inclusion, nor for promoting positive change while moving forward.
Boards should be willing, indeed eager, to fire a CEO who’s building an empire instead of building value.
As far as we individual investors are concerned, the reality is that we are going to be minority shareholders with approaching zero control over a company we invest in or speculate in. We should have no foolish delusions otherwise. Which is why the first P of Doug Casey’s Nine Ps of Resource Stock Evaluation is so important. People.
Do the People in a company you might invest in have a history not only of “successes” but of providing return on investors’ capital? What are they seeking the next investment round for? Is it to keep feeding management? Or is it to increase the value of the company in a way that—as a matter of primacy—is designed specifically to improve the likelihood or amount of return to the investors?
Does the management want to grow their empire, or do they want to grow your wealth?
Ask management: when the company finally starts making money, how do you intend to get it to your shareholders?
The most common answer is: let’s not lean too far over our skis, meaning, they don’t think that is important yet, with the profits being speculative and so far away.
My preferred answer is: we think about that every day, because that is the purpose of this whole venture. The specifics of how they will do so are not the important part of the answer yet. But what I seek with my question is intent. I’d like them to recognize the purpose at the get-go.
If they aren’t in it primarily for profit for their investors, then they shouldn’t pretend they are. They should open a non-profit or perhaps a B corp.
As we say in the beginning of our novel, Speculator: a junior mining company takes their dream and your money and turns it into their money and your dream.
Don’t let them. Instead, pick the right companies, led by the right people. People who are good, honorable, successful, and whose incentives are aligned with rewarding their investors. Us.
Find the rare company where that discipline actually holds, and you’ve found something worth owning through the crises ahead.
At Crisis Investing, we work to help you do just that.
Sincerely,
John Hunt, MD
Editor, Doug Casey’s Crisis Investing
Excellent point. Clearly defined.
The pattern is clear: identify serially successful people and invest alongside them.